Welcome to the Crunch Lab Pilot Program
The Crunch Lab is Justin's pilot program for offering customized, 1-on-1 tax planning & financial modeling services for individuals. In this program, I’m looking for 3 to 5 people or couples (of any filing status) who are interested in having me build out a tax and financial planning model that is custom tailored to their specific facts and circumstances.
In the Crunch Lab Pilot Program, I am most interested in working on the following items:
Multi-Year Tax Planning: this would involve a lifetime, forward-looking analysis designed to take into account all expected sources of income and deduction and develop a year-by-year strategy to minimize your lifetime tax burden through the use of (1) Roth IRA conversions, (2) capital gain and loss harvesting, (3) Social Security & pension claiming analysis (if applicable), (4) RMD planning and (5) IRMAA considerations.
Current-Year Tax Strategy: this would involve a projection of the current year's federal tax liability, including estimated payments, withholding adjustments, and timing of income recognition.
Account Location Strategy: this would involve review of which asset types belong in taxable, tax-deferred, and tax-exempt accounts to maximize after-tax returns.
Withdrawal Sequencing: this would involve a year-by-year playbook for which accounts to draw from first (taxable → tax-deferred → Roth, or more nuanced approaches) to minimize your lifetime tax bill.
Retirement Cash Flow Projection: this would involve a year-by-year model of projected withdrawals, showing how Social Security, pensions, RMDs, Roth distributions, and other income sources combine through life expectancy.
Simplified Explanation: I will take all of your financial details and build out a model that takes you from today, through the Personal Tax Planning Template and then through various retirement funding / distribution calculators, such as the 4% Rule, the Guardrails Approach, the Bucketing Approach, Time-Sequenced Distributions and perhaps others.
Summary Explanation: (1) where does all the money come from? (2) how does it all run through the tax line in the most efficient way possible? (3) how does it get distributed out to fund a desired retirement spending level and (4) how do we combine all of those things together to create the most residual after-tax value at the end?
The 4 Pillars of The Crunch Lab Program
Pillar 1 - Confidence That You're Not Leaving Money On The Table
For many folks that are reading about The Crunch Lab Program today, my guess is that the primary financial concern you have is NOT "will I have enough money to last through retirement?"
You already know that you have plenty. You live a modest lifestyle and your retirement accounts and other retirement income will be more than enough to see you through to the end. Rather, the issue is "am I leaving money on the table?"
Are you missing conversion windows that are quietly closing?
Are you drawing down accounts in the wrong order and with the wrong timing?
Do you have investments bucketed in the wrong kind of accounts?
Are you harvesting the correct investments now, while also leaving others appropriately alone so they can receive step-up in basis upon death?
Are you maximizing your after-tax cash flow & net worth?
Two people with identical financial situations can both "be fine" in retirement, while one hands over tens of thousands of dollars more to the government over their lifetime. Both individuals may even take identical financial steps. But one of them might take the "right steps" at the "wrong time." Timing matters. And to get the timing right you have to plan ahead.
Two couples can be dining on the same Filet Mignon & lobster tails in the evening, after drinking the same Margaritas on the same golf course in the morning. But one is paying significantly more for the privilege, in the form of quiet account erosion through unnecessary taxation, that they never even realize is happening.
Pillar 2 - Clarity On The Full Picture, Not Just The Pieces
You've already done the hard part. You've gathered every piece of financial data you have, entered it into the Personal Tax Planning Template, and built out a model that puts your entire financial life on one screen. The pieces aren't scattered anymore. They're assembled. So why does it still feel like something's not clicking?
Think of it like this.
You decide to cook a complex dish from scratch — something with 15 ingredients and a two-page recipe. You go to the store and buy everything on the list. You come home, lay it all out on the counter, and follow the instructions step by step. You measure correctly. You don't skip anything. And when it's done, it's... fine. It's edible. But you know it's not what it is supposed to taste like. Then you watch a seasoned chef make the exact same dish with the exact same ingredients and the exact same recipe — and somehow theirs is completely different. Not because they had better ingredients. Not because they had a secret recipe you didn't. But because they understood which flavors were building on each other, which ones were competing, when to hold back on the heat, and when to let something reduce a little longer. The difference wasn't the pieces. It was knowing how the pieces talk to each other.
That's where a lot of people find themselves. The data is all there. The model is built. But reading it — really reading it, the way someone who's lived in these numbers for years reads it — takes a level of pattern recognition that doesn't come from following the instructions. It comes from experience. From having seen hundreds of different combinations of income, deductions, conversions, and thresholds and knowing intuitively what the model is telling you to do next. The Crunch Lab doesn't give you better ingredients. It gives you the chef.
Pillar 3 - A Sounding Board Who Speaks Your Language
You're not a beginner. You know what a Roth conversion is. You understand marginal tax brackets. You've read about IRMAA. You watch Number Crunch Nerds religiously on Saturday mornings. You've probably forgotten more about tax planning than most people will ever learn.
And that's exactly what makes this so frustrating — because the more you know, the harder it is to find someone worth talking to about it. You've tried bringing questions to your CPA and gotten a blank stare or a surface-level answer that you already knew before you asked. You've sat in front of a financial advisor who wanted to talk about asset allocation and risk tolerance questionnaires when all you wanted was to pressure-test a conversion strategy. You've Googled it, watched the YouTube videos, read the forum threads — and walked away with six different opinions and no way to know which one actually applies to your situation.
What you don't have is someone you can sit across from and say, "Here's what I'm thinking — does this make sense for my numbers?" Someone who won't start from scratch explaining the basics, but who can meet you where you are and go deeper. Someone who can listen to your logic, pull up your actual model, and say, "Yes, that works — but have you considered what it does to your IRMAA in year three?" or "That's a good instinct, but here's why the timing is off by one year."
Someone who will challenge your thinking when it needs to be challenged, confirm it when it's right, and show you the difference on screen — not with an opinion, but with a model built on your numbers that makes the answer undeniable either way.
Pillar 4 - Permission To Actually Spend Your Money
This one doesn't get talked about enough. You spent 30 or 40 years accumulating, and now you're supposed to flip a switch and start spending — but every withdrawal feels like you're chipping away at something you built. The habits that got you here — the discipline, the saving, the "do I really need this?" mindset — those don't just disappear because you turned 65. They follow you into retirement and they whisper in your ear every time you think about booking the trip, remodeling the kitchen, or helping one of the kids with a down payment.
So you underspend. You skip the trip. You second-guess the renovation. You tell yourself you'll do it next year when you have a better handle on things. But next year comes and the hesitation is still there — not because anything changed, but because nothing did. You still don't have a clear picture that says, with certainty, "Yes. You can do this. And here's exactly why it doesn't jeopardize anything."
That's the quiet cost of not having a plan. It's not always a dollar amount you can point to. Sometimes it's the vacation you didn't take. The years you spent being more careful than you needed to be. The experiences you postponed that you can't get back. Not because the money wasn't there — but because no one ever showed you, in black and white, that it was.
A good plan doesn't just tell you how to save on taxes. It tells you what your money can actually do for you — how much you can spend, in which years, from which accounts, and what's still left standing at the end. It replaces the guesswork with a number. And once you see that number, the guilt goes away. Because you're not guessing anymore. You're deciding — with the math behind you.
Does The Crunch Lab Give Me a Comprehensive Financial Plan?
There are some elements of a Comprehensive Financial Plan which are beyond the scope of The Crunch Lab Program. You should consider each of these items when deciding whether this program will help you meet your financial planning needs.
The following items are "out of scope" for The Crunch Lab Program:
Trust Planning: This includes analysis of whether revocable or irrevocable trusts are appropriate for probate avoidance, asset protection, special needs, generation-skipping or any other purposes for which a trust structure may be appropriate.
Estate Planning Review: This includes confirmation that wills, trusts, powers of attorney (financial and healthcare), healthcare directives, and beneficiary designations are current, coordinated, and reflect your actual wishes.
Beneficiary Designation Audit: A line-by-line check of every account's primary and contingent beneficiaries against the estate plan.
Property and Casualty Insurance Review: An assessment of homeowner's, auto, umbrella, and any specialty policies (rental property, business) to confirm coverage limits are appropriate and cost-effective.
Life Insurance Needs Analysis: A calculation of the income replacement, debt payoff, and estate liquidity needs that would arise at death, matched against existing coverage and whether policies should be maintained, reduced, or replaced.
Disability Income Protection: A review of employer-provided and individual disability policies to ensure adequate income replacement during working years, especially for self-employed or high earners.
Long-Term Care Planning: An evaluation of self-insuring versus traditional LTC insurance versus hybrid life/LTC policies, factoring in health status, family history, and asset protection goals.
Health Insurance Bridge Strategy: For early retirees (pre-65), a plan covering ACA marketplace options, COBRA, or employer retiree coverage, including premium subsidy management tied to MAGI.
Risk Tolerance Documentation: A formal assessment that captures both your willingness and ability to bear risk, revisited as circumstances change.
Behavioral and Contingency Planning: Written guardrails for market downturns, health crises, job loss, or family changes — so decisions aren't made emotionally in the moment.
While these components of a Comprehensive Financial Plan will not be directly addressed as part of The Crunch Lab Program, the quantitative results obtained from this program may allow you to address any/all of the items above in a more informed manner.
For example, by understanding "your numbers" as a result of The Crunch Lab Program, you will be able to make more informed decisions about the adequacy of your various types of insurance needs and the extent to which your financial plan needs to include trust structures and other estate planning items.
How Will The Crunch Lab Pilot Work?
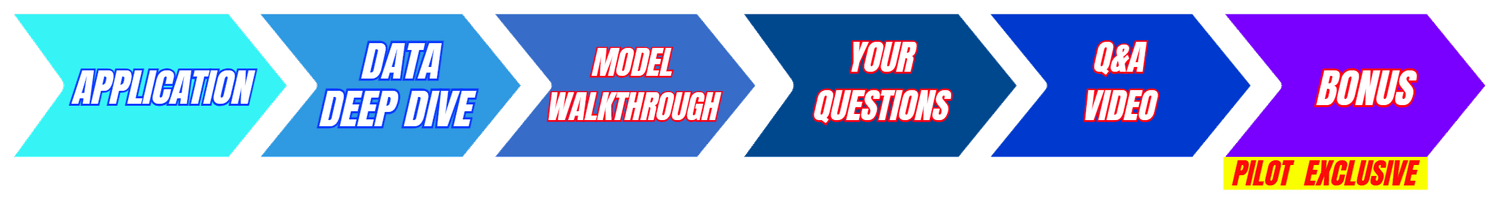
Phase 1 — Application & Fit Assessment
Before any work begins, we need to make sure this is the right fit — for both of us. Here's how that process will work:
You apply to the program by submitting a $100 application fee. This fee is not an additional cost — it will be applied toward your program purchase if we move forward with working together.
I send you a summary questionnaire designed to give me a clear snapshot of your financial situation, your goals, and the areas where you are looking for the most help. This isn't the deep, data-gathering phase — it's a high-level overview so I can understand what your plan would involve and whether the Pilot Program is the right vehicle for it.
You complete the questionnaire and return it to me. Take whatever time you need to answer thoughtfully — there is no deadline pressure here.
I review your answers and make a determination. If I believe we are a good fit to work together in the Pilot Program, I will send you a link to purchase the full program. Your $100 application fee will be credited toward the purchase price.
If I determine for any reason that we are not a good fit — whether it's a scope issue, a complexity issue, or simply a matter of the pilot not being the right format for your situation — I will let you know and refund your $100 application fee in full. No hard feelings, no questions asked.
One important note: if at any point between submitting your application fee and receiving the full-program purchase link, you decide not to move forward with working together, the $100 application fee becomes non-refundable. This policy exists because I'm investing time to review every application, and I need to know that applicants are serious about participating when they apply.
Phase 2 — Deep Data Gathering
Once we agree to work together in the Pilot Program and you complete your program purchase, I will send you a detailed questionnaire that covers every corner of your financial life. Income, expenses, accounts, tax returns, retirement benefits, investment positions, future plans — all of it. If it touches your tax picture or your retirement cash flow, it's in there. The questionnaire will be thorough by design, because the model I'm building for you is only as good as the information that goes into it. Incomplete data leads to incomplete answers, and that's not what either of us is here for.
Take your time with it. There's no deadline and no pressure to have everything perfect on the first pass. If you're unsure about a number, give me your best estimate and flag it. If you need to dig up a document you haven't looked at in a while, that's fine — make a note and we'll circle back. The goal isn't perfection on day one. The goal is to get a complete and honest picture of where you stand so that when I sit down to build your model, I have everything I need to do it right. Anything that's missing or unclear, I will follow up on directly during the model build-out phase.
Once your questionnaire is complete and I have everything I need, I build your model. This is the behind-the-scenes phase you won't see in real time — where I take your raw data and construct a fully integrated, year-by-year financial model tailored to your specific situation. Depending on the complexity of your financial picture, this step may take several weeks. When it's ready, we move to Phase 3.
Phase 3 — Model Walkthrough
Once the model is complete, I'll record a detailed video walking you through every aspect of it, step by step. This isn't a five-minute summary with a few pie charts and a green checkmark that says "you're on track." This is a full screen-share walkthrough where I open your actual model on screen and show you exactly what it says about your situation — your projected tax liability year by year, where your Roth conversion opportunities are, how your withdrawal sequence is structured, what your IRMAA exposure looks like, how your income sources layer on top of each other, and where the biggest opportunities for tax savings exist. I'll explain the logic behind every recommendation — not just what the model says to do, but why it says to do it, and what would change if we pulled a different lever or adjusted an assumption.
Because this is a recorded video — not a live meeting — you control the pace. You can pause it to absorb a section before moving on. You can rewind and watch a piece again if something didn't click the first time. You can take notes without worrying about falling behind. And six months from now, when you're sitting at your desk and trying to remember why the model recommended a specific conversion amount in a specific year, you don't have to rely on your memory or dig through a stack of meeting notes. You press play and hear me explain it again, in full detail, with your numbers on the screen — as many times as you need. The walkthrough isn't just a presentation. It's a permanent reference that stays useful for as long as the model is relevant to your life.
Phase 4 — Your Questions
After you've watched the walkthrough, take a beat. Let it sit for a few days. Watch it again if you need to. Let the information settle and give yourself time to think about what you've seen — because the best questions don't come in the first five minutes. They come later, when you're lying in bed replaying something I said about year seven, or when you're on a walk and suddenly realize you forgot to ask about what happens if your spouse claims Social Security at a different age. That's when the real questions surface. Write them all down. Every single one. No question is too small, too obvious, or too "what if" to include.
These might be clarification questions — why does the model recommend that specific conversion amount in that specific year and not more? They might be scenario questions — what changes if I retire at 63 instead of 65, what happens if I sell the rental property in 2028 instead of holding it, what does the picture look like if we assume 4% inflation instead of 3%? They might be implementation questions — how do I actually execute a Roth conversion with my custodian, what do I tell my CPA, what order do I do these things in? Or they might be questions you didn't even know you had until you saw your numbers laid out on a 30-year timeline for the first time. Whatever comes up, compile them all into one list and send it over. The more thorough your list, the more thorough my response will be.
Phase 5 — Q&A Video
Once I have your questions, I'll record a second video dedicated entirely to answering them — every single one, in the order you sent them, with your model open on screen so you can see exactly how each answer connects back to your actual numbers. This isn't a generic FAQ. If you asked why the model shows a smaller conversion in year nine, I'll pull up year nine and walk you through exactly what's happening with your income, your bracket, and your IRMAA threshold in that specific year. If you want to know what happens when you change a variable, I won't just tell you — I'll change it in the model, on screen, and let you watch the numbers move in real time. You'll see the cause and the effect, not just a summary of the conclusion.
If any of your questions require me to build out alternative scenarios — a different retirement date, a different claiming strategy, a different assumption about returns or inflation — I'll build those into the model and walk through them side by side so you can compare the outcomes directly. You won't be left guessing which path is better based on a verbal explanation. You'll see Path A and Path B next to each other, in your numbers, with the differences highlighted. And just like the Phase 3 walkthrough, this video is yours to keep. When the time comes to actually make one of these decisions — maybe a year from now, maybe three — you can pull it back up and revisit the exact reasoning behind each recommendation before you pull the trigger.
Phase 6 — Second Round Q&A (Pilot Program Exclusive)
Because this is a Pilot Program, there's a built-in second round of questions and answers that won't necessarily be part of the standard Crunch Lab offering down the road. Here's why it matters: after you've watched the Phase 3 walkthrough, submitted your first round of questions, and received the Phase 5 Q&A video, something interesting tends to happen. The answers to your first set of questions generate a new set of questions you didn't know you had. Maybe the alternative scenario I modeled in Phase 5 opened up a path you hadn't considered and now you want to explore it further. Maybe seeing the side-by-side comparison changed your thinking about when to claim Social Security and you want to see how that ripples through the rest of the plan. Maybe your spouse watched the videos and has an entirely different set of concerns that need to be addressed. That's normal — and it's exactly why this second round exists.
In Phase 6, you'll compile a second list of questions and send them over, just like you did in Phase 4. I'll record another video walking through each one — same format, same level of detail, same on-screen model work. This second pass is where the plan really gets pressure-tested, because by this point you've had time to live with the information, think about it, talk about it with your spouse or your CPA, and come back with the deeper, more nuanced questions that only surface after the initial fog clears. Pilot participants get this extra round because the whole point of the pilot is to go deeper, refine further, and make sure you walk away from this process with a level of understanding and confidence that wouldn't be possible in a single pass. Consider it one of the perks of getting in early.
Interested in Participating in The Crunch Lab Pilot Program?
Tax Only
$2,497
This tier focuses exclusively on the tax planning components of The Crunch Lab. Ideal if your primary concern is minimizing your lifetime tax bill and you're less focused on retirement cash flow modeling, distribution strategy, and investment placement optimization.
Multi-year tax planning with Roth conversion sequencing, capital gain/loss harvesting, RMD projections, IRMAA threshold tracking, and Social Security/pension claiming analysis
Current-year federal tax liability projection with estimated payment and withholding review
Detailed questionnaire and collaborative model build
Recorded video walkthrough of your completed model
Written Q&A submission followed by a recorded video answering all of your questions
Includes Phase 6 - Second Round Q&A (Pilot Program Exclusive)
Does not include: account location strategy, withdrawal sequencing, retirement cash flow projection, or distribution strategy modeling.
Full Plan
$4,997
$3,497
(pilot program pricing)
This is the complete Crunch Lab experience. Everything in the Tax Only tier, plus account location optimization, full retirement cash flow modeling, and withdrawal sequencing — giving you a unified, year-by-year view of how your money is positioned, how it moves, and how it gets taxed from now through life expectancy.
Includes everything in the Tax Only tier, plus:
Account location strategy — a review of which asset types belong in taxable, tax-deferred, and tax-exempt accounts to maximize your after-tax returns
Withdrawal sequencing — a year-by-year playbook for which accounts to draw from, in what order and in what amounts, to optimize your lifetime tax bill
Retirement cash flow projection — a complete model showing how Social Security, pensions, RMDs, Roth distributions, and other income sources combine to fund your desired spending level through life expectancy
Distribution strategy modeling using frameworks such as the 4% Rule, Guardrails, Bucketing, and Time-Segmented approaches — compared side by side so you can see which approach best fits your situation
Inflation and longevity stress testing across multiple scenarios
The Full Plan is recommended for anyone who wants the complete picture — not just how to minimize taxes, but how your assets should be positioned across account types, which accounts to tap and when, and how everything works together as a coordinated, year-by-year game plan through the end of retirement.
FAQs
The ideal participants for the pilot program are folks who generally meet these criteria:
You want to operate in the middle-ground between 100% DIY and 100% Fully Delegated financial planning : Folks in this category want someone they can work back-and-forth with to develop a lifetime financial plan, while retaining full control over the final decision making process, strategy implementation and management of assets.
You want to develop a working relationship with someone which extends beyond the initial plan setup: Folks in this category want to work with someone who will keep their plan updated - likely once per year - but possibly as much as quarterly, depending on the situation.
You are interested in working with Justin from Number Crunch Nerds: Folks in this category enjoy Justin's teaching style, YouTube channel, membership programs and want to build a closer working relationship.
You have been in the Personal Tax Planning Template program for at least 3 Months: I'm only interested in working directly with folks who want to work directly with me. My belief is it would be difficult for you to know if you want to work directly with me, if you've not been part of the Personal Tax Planning Template program for at least 3 months.
You are roughly in the 50 - 75 years old age range: While I will be open to developing plans for folks who are either earlier in their working years or much later into retirement and already in RMDs, once the full Crunch Lab Program is launched. For purposes of the Pilot Program, I think this age range would be most appropriate for the topics that I want to be the central focus of the pilot.
Depending on your situation, the following items could become part of your Pilot Plan:
Net Worth Statement: A snapshot of all assets minus all liabilities, establishing the baseline for every recommendation that follows.
Cash Flow Analysis: A month-by-month accounting of income sources versus fixed and discretionary expenses, identifying how much surplus is available to save or invest.
Goal Identification and Prioritization: Specific, dated targets (retirement age, home purchase, education funding, travel) ranked by importance so trade-off decisions have a framework.
Emergency Fund Assessment: An evaluation of whether liquid reserves cover 3–6 months of essential expenses, and a plan to close any gap.
Debt Management Strategy: A review of all outstanding debts (mortgage, auto, student, credit) with a payoff or refinancing plan that factors in interest rates, tax deductibility, and opportunity cost.
Charitable Giving Strategy: Evaluation of donor-advised funds, qualified charitable distributions, charitable remainder trusts, and bunching strategies to maximize both tax benefit and philanthropic impact.
Inflation and Longevity Stress Testing: Scenarios modeled at different inflation rates and life expectancies (including one spouse surviving to 95+) to test whether the plan holds under adverse conditions.
Since this is a Pilot Program, I am open to ideas and suggestions regarding things you may be interested in including in your plan. There is a link further down on the page where you can submit ideas for this program.
The core deliverable is a fully functional, Excel-based tax and financial planning calculator — built specifically for you, around your data, and designed to be a working tool you can use long after the pilot is complete. This is not a PDF report that sits in a drawer. It's not a summary document with a few charts and a cover page. It's a living, breathing spreadsheet that you can open, interact with, update, and reference for years to come.
The calculator will incorporate some or all of the following components, depending on what your situation requires: the Personal Tax Planning Template, the Financial & Retirement Planning Calculator, and various retirement funding and asset distribution calculators — including frameworks like the 4% Rule, the Guardrails Approach, the Bucketing Strategy, Time-Segmented Distributions, and potentially others. All of these will be packaged into a single, integrated file where everything works together. Your income flows into your tax projections. Your tax projections inform your conversion strategy. Your conversion strategy connects to your withdrawal sequence. Your withdrawal sequence feeds into your retirement cash flow. One file. One connected model. Change an assumption in one place and watch the impact ripple through every other component.
Beyond the existing tools, your deliverable may also include new calculators or worksheets that I build specifically for your situation. If your financial picture involves something that doesn't fit neatly into the existing framework — an unusual pension structure, a deferred compensation arrangement, a phased retirement timeline, rental income with specific disposition plans — I'll build what's needed to capture it. The exact components included in your file will be determined by the complexity and specifics of your financial life. No two pilot participants will receive an identical deliverable, because no two participants have an identical situation.
But here's the part that makes this different from anything else you'll find: the deliverable doesn't just include the calculator. It includes you actually understanding how to use it. Every pilot participant will receive detailed, recorded instructional videos that walk you through the calculator step by step — how each section works, how the components connect to each other, what the key inputs are, how to interpret the outputs, and what to look for when something changes in your life and you need to update the model. These aren't generic tutorial videos that apply to everyone. They're recorded specifically for your build, referencing your numbers, your tabs, and your results. So when you sit down six months or a year from now and need to revisit a decision, you don't have to guess what a number means or try to remember what I told you. You press play and I walk you through it again — as many times as you need.
What you're ultimately walking away with is not a plan that someone made for you. It's a tool that belongs to you — one you understand, one you can use, and one that stays relevant as your life evolves.
As everyone reading this knows, the Personal Tax Planning Template program is built using xls format. I have the ability to build your customized calculator in either xls or xlsx. I do not have the ability to build the calculator directly in Sheets, Numbers, LibreOffice or any other program. Only Excel in the two formats mentioned. If you can use the PTPT in your spreadsheet program of choice, then you will be able to use the customized calculator, as it will built in the same conceptual way, which includes:
No macros
No VBA code
No add-ins
Formatting will be kept as simplistic as possible
The application fee serves two purposes. First, it separates people who are genuinely interested in participating from those who are casually browsing. Because I'm only working with 3 to 5 participants in this pilot, I need to know that everyone who applies is serious about going through the full process. Second, the application fee is not an additional cost — it will be applied in full against the total program fee if you're accepted into the pilot. Think of it as a deposit that confirms your intent, not a charge on top of the program price.
Here's how the refund works: if I review your summary questionnaire and determine for any reason that we're not a good fit to work together in the Pilot Program, your $100 application fee will be refunded in full — no questions asked. However, if at any point between submitting your application and receiving the final purchase link you decide on your own not to move forward, the $100 application fee becomes non-refundable. This is because I'm investing time in reviewing every application and responding thoughtfully, and I need to know that the people in the pipeline are genuinely committed to the process when they apply.
No - I am not offering any services with respect to preparing or filing Federal, state or any other types of tax returns, forms or schedules with any taxing authority. For these types of services I recommend you use your own CPA or other tax preparation professional.
No - this includes significant business tax planning, business succession, exit planning, entity valuation, buy-sell agreements, key-person insurance and the tax implications of any sales, mergers or acquisition structures.
Exception - insignificant business activities that you may participate in, such as Schedule C businesses or flow-through items from Partnerships and S-Corporations which are ancillary in nature to the rest of your financial picture are OK for the Pilot Program. To be evaluated on a case-by-case basis. If you have questions specifically on this, reach out to me at justin@numbercrunchnerds.com
Note - farm & agricultural business activities is a highly specialized area and will not be included in The Crunch Lab at any time.
If you can get just $35,000 across the tax line at a 10% rate differential (for example 32% vs 22% or 24% vs 12%) over the 13.5 years between age 59.5 and 73, that tax savings of $35,000 x 10% = $3,500 pays for your admission to the Full Pilot Program. Everything saved above that is gravy baby.
Because this process has too many moving parts to cram into a 60-minute meeting where you're frantically scribbling notes while trying to absorb information in real time. Think about the last time you sat down with a financial advisor or CPA. You walked in with a mental list of things you wanted to ask. The conversation moved fast. You wrote down what you could. You nodded at things that sounded right but weren't entirely sure about. And you walked out with a legal pad full of half-finished notes, a few scribbled numbers you can't quite place, and the nagging feeling that you forgot to ask the one question that was actually keeping you up at night.
That's not how The Crunch Lab works. In this program, you have the time to sit down, think through your questions carefully, and write them out in a way that captures exactly what you want to know — without the pressure of a ticking clock or a meeting that's running over. And when I respond, it's not a verbal answer that evaporates the moment the meeting ends. It's a recorded video walkthrough where I pull up your actual model on screen, address each question one by one, and show you the answer in real numbers. You can pause it. Rewind it. Watch it again six months from now when you're ready to make a move and want to revisit the logic. Try doing that with a set of meeting notes you scribbled on a napkin from Chipotle Grill.
The bottom line is this: you don't need live interaction with my coffee breath and bow-tie in order to understand your financial plan. What you do need is someone who communicates clearly, thoroughly, and in a format you can refer back to again and again — long after the conversation is over. That's exactly what this process is designed to deliver.
The only exchange of personally identifying information involved in this engagement will be as follows: (1) Your Name – for purposes of signing your engagement letter and (2) Your Age – for purposes of calculating RMD or Social Security start dates or other tax matters where age is a relevant factor. Your name and age will not be shared by me with any other individual or company and will not be used for any other purposes than those listed above.
No other personally identifying information will be exchanged. This engagement does not involve (1) preparing or filing any forms, (2) managing any assets or affairs. Therefore I will not need to know your Social Security Number, account numbers or address. If the engagement requires me to look at any documents or forms, I request that you simply black-out or otherwise redact all personally identifying information.
Although I may use blank copies of calculators or schedules that I create on your behalf for purposes of my YouTube channel, your personal fact pattern and images or videos of your numbers in action that come from The Crunch Lab Program will not be used by me for any purposes beyond the scope of providing you services under this engagement. Your engagement and financial plan are for you and you only.
Videos that I record for you will be housed on a systeme.io page that only you have access to.
1. You're getting in at the ground floor — and that works in your favor.
The Personal Tax Planning Template and the financial calculators that power The Crunch Lab have been built from scratch over the past three years as part of various Number Crunch Nerds programs. Until now, they've only been used as DIY tools. This pilot is the very first time I'm taking someone's real-world data — their actual accounts, their actual income, their actual tax situation — and building and modifying these tools specifically around them. That means you're not walking into a polished, pre-packaged system where I plug your numbers into a template and hand you a printout.
You're walking into a workshop where I'm actively shaping the tools around your situation. That process requires a level of close, back-and-forth coordination with you that simply won't exist once the consulting versions of these products are finished and the structure is more standardized. Once the framework is locked in, future clients will benefit from a more streamlined process — which is great for efficiency, but it also means less direct interaction with me during the build. Pilot participants get the opposite: more questions, more dialogue, more refinement, more of my time and attention focused specifically on making your model as precise as it can possibly be. That window closes once the pilot is over.
2. You're not on an assembly line.
We've all heard the stories. You pay a financial planner several thousand dollars. You sit through two or three meetings. You fill out a risk tolerance questionnaire. And a few weeks later you receive a 60-page bound report that looks impressive on the shelf but doesn't actually answer the specific questions that were keeping you up at night. The charts are generic. The recommendations are broad. And when you try to dig into the details, you realize the plan was built from the same template they use for every client, with your name dropped in at the top. That's the assembly line model — and it exists because most planning firms are trying to serve hundreds of clients with a handful of advisors. The math doesn't allow for depth.
The Crunch Lab Pilot Program is the opposite of that. I'm working with 3 to 5 people (or couples). Not 50. Not 200. Three to five. Every model is built by me, from scratch, around your specific facts. Every walkthrough video is recorded by me, speaking directly to your situation. Every question you submit gets a detailed, personalized response — on screen, in your model, with your numbers. There is no junior analyst doing the work while I show up for the final presentation. There is no template with your name swapped in. It's your data, your plan, and my full attention.
3. You have influence over the direction this program takes.
Because the Pilot Program is, by design, a beta test, nothing is set in stone. The structure is intentionally flexible. If you're going through the process and you want to see a specific scenario modeled — a different retirement date, a different Social Security strategy, a "what if we sell the house in year four" analysis — there's a very good chance I can build it. If you have ideas about how the deliverable could be more useful, I want to hear them. If there's an angle I haven't thought of that matters to your situation, that's exactly the kind of feedback that makes the pilot valuable for both of us.
Future participants in the full Crunch Lab Program will benefit from a more defined scope and structure — which is a good thing. But it also means they'll have less room to shape what they receive. Pilot participants are helping me build this program while simultaneously getting the most customized, most hands-on version of it that will ever exist. Once the pilot is over and the program is formalized, this level of flexibility and personal access won't be available at the same price point — or possibly at all.
Interested But Not Sure You're Ready To Apply Today?
Add your name to the Interest List for further communications about The Crunch Lab
Number Crunch Nerds | 2026
justin@numbercrunchnerds.com